

Earlier this year, a 22-foot statue of Donald Trump, finished in gold leaf, was unveiled at the president’s golf resort outside Miami. Time reports the $450,000 monument was paid for by crypto investors, and Trump called in to address the crowd. The man photographed cutting the ribbon was Brock Pierce - a former child actor turned crypto entrepreneur, a co-founder of the stablecoin giant Tether, and, according to the files the Justice Department released from Jeffrey Epstein’s estate, a business friend of Epstein’s for nearly a decade, the man who brought Epstein’s money into Coinbase.
A figure like that holding the scissors at the president’s resort is not an accident of the guest list. It is a fair summary of the past two years. Since the 2024 election, the crypto industry has received presidential pardons for its convicted executives, permanent dismissal of the government’s lawsuits against it, custody of the offices that regulate it, and a federal law written to bless its most profitable product. The president’s family, meanwhile, entered the industry itself and extracted billions of dollars from it - including from a company whose founder the president pardoned while insisting he’d never heard of him.
None of what follows is inference. It is court records, Justice Department files, congressional letters, lobbying disclosures, and the president’s own signed financial statements. The story they tell, assembled in order, is of a government that stopped policing an industry at the exact moment the men who run that government started profiting from it.
The pardons
Begin with a Friday at the end of March 2025, when a $100 million debt to the United States came due and was never paid.
A federal judge had imposed the fine on HDR Global Trading, the company behind the crypto exchange BitMEX - a marketplace for trading digital currencies, the way a stock exchange handles stocks. The company and its three founders had pleaded guilty to willfully ignoring the anti-money-laundering laws that require financial platforms to know who their customers are. Prosecutors said they ran the exchange as a “money laundering platform” where, at times, an email address was the only identification needed to trade. With hours left before the payment deadline, Trump pardoned the founders - and the corporation itself.
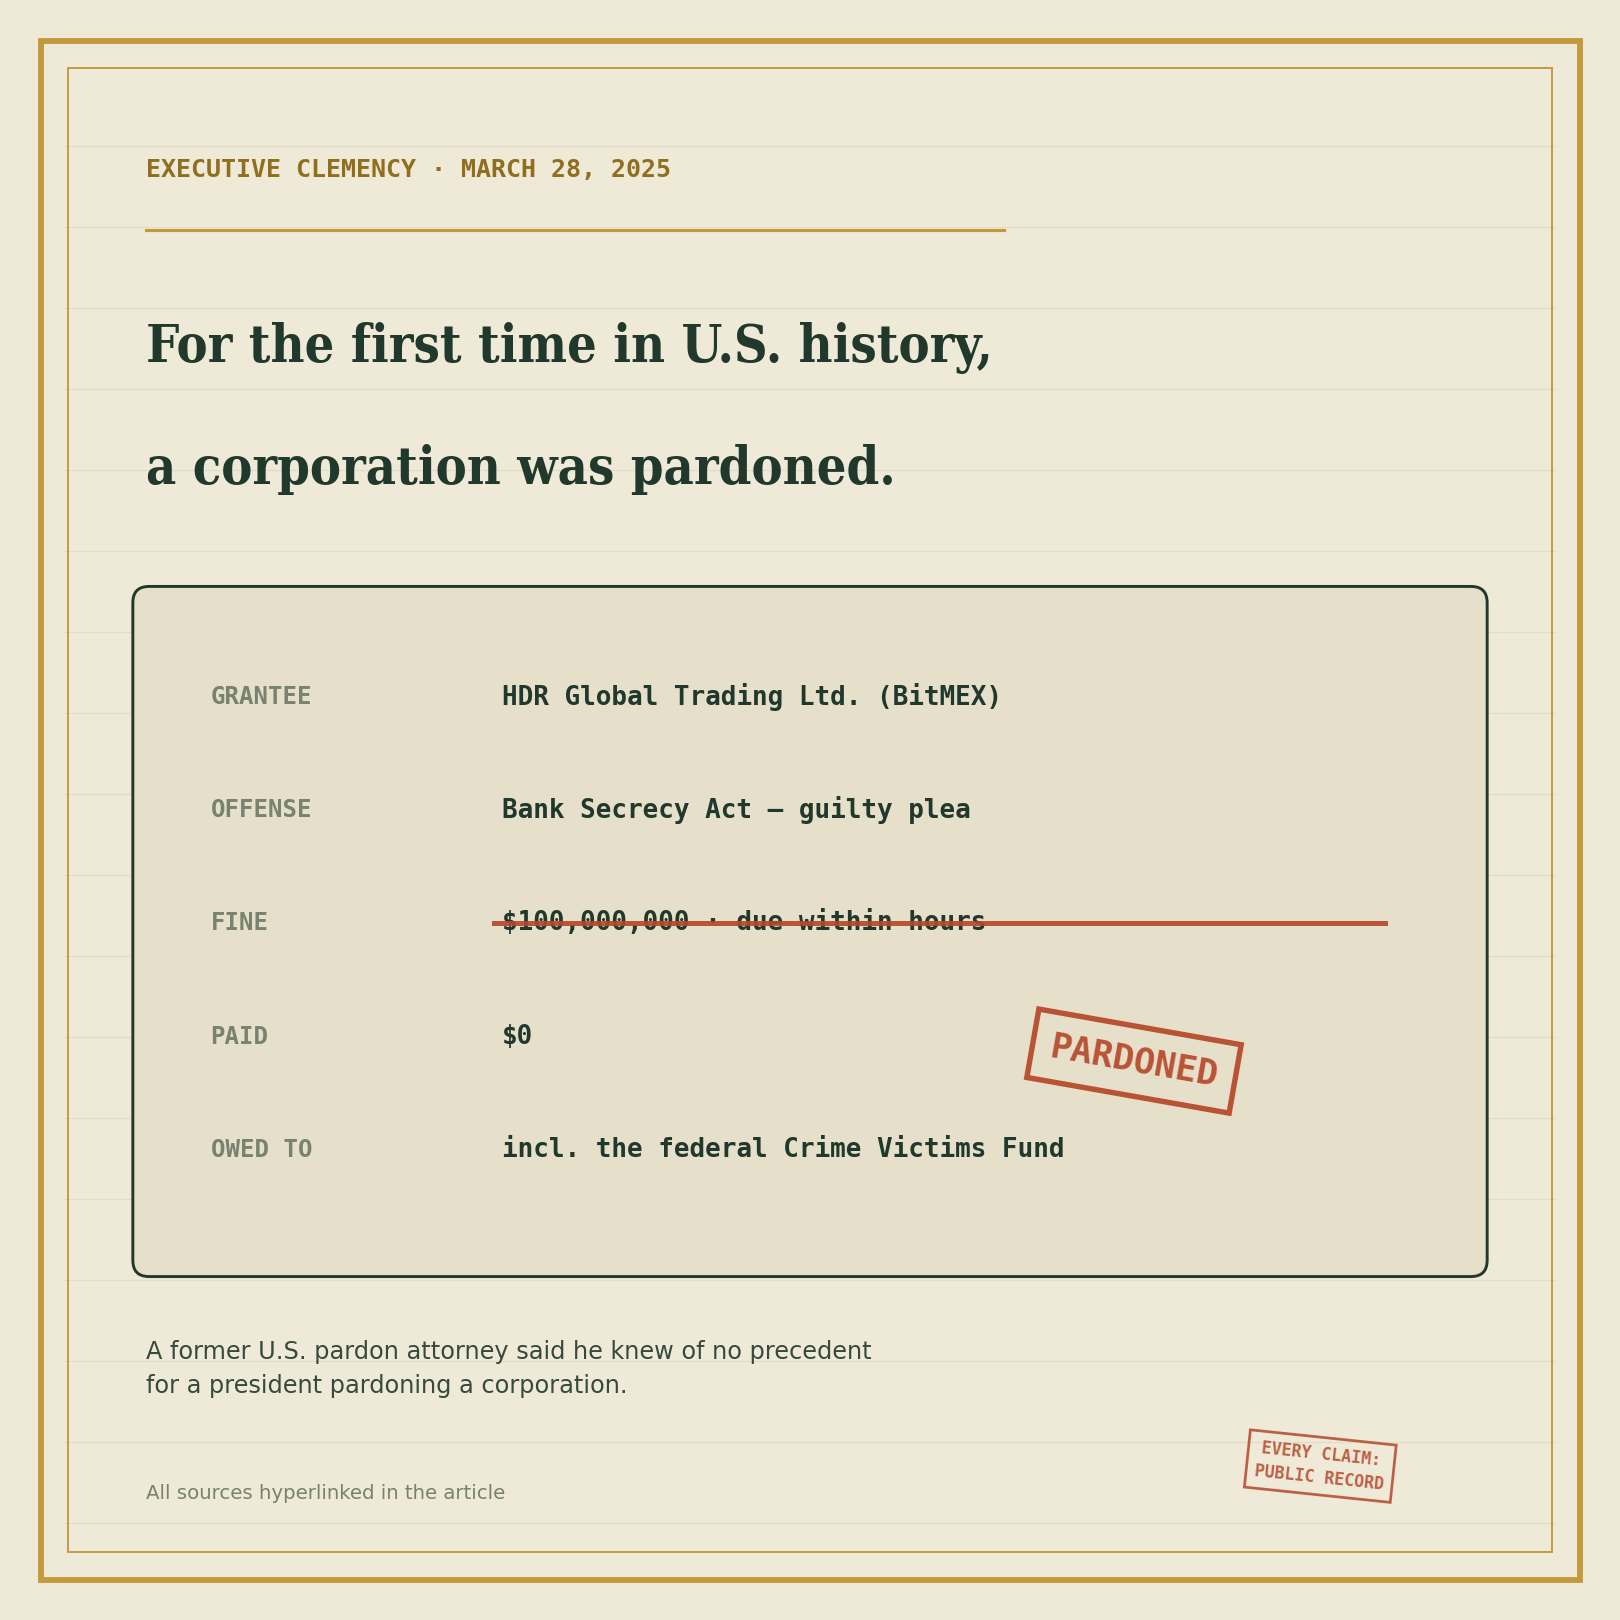
That last part had never happened before. Legal scholars, including a former U.S. pardon attorney, could identify no prior instance of an American president pardoning a corporation, in the country’s history. The erased fine would have flowed in part to the Crime Victims Fund - the federal account that compensates victims of violent crime.
The clemency had started even earlier. Days into the term, Trump freed Ross Ulbricht, serving a double life sentence for building Silk Road, the dark-web market the Justice Department called “the most extensive and sophisticated criminal marketplace on the internet” - roughly a billion dollars in commerce, mostly narcotics, mostly paid in Bitcoin. Ulbricht was a hero to the crypto and libertarian movements, and his release had been a campaign promise. Whatever one thinks of a double life sentence, the pardon was not a correction of fact. The man ran a billion-dollar drug market, and the government now describes people like him as the persecuted.
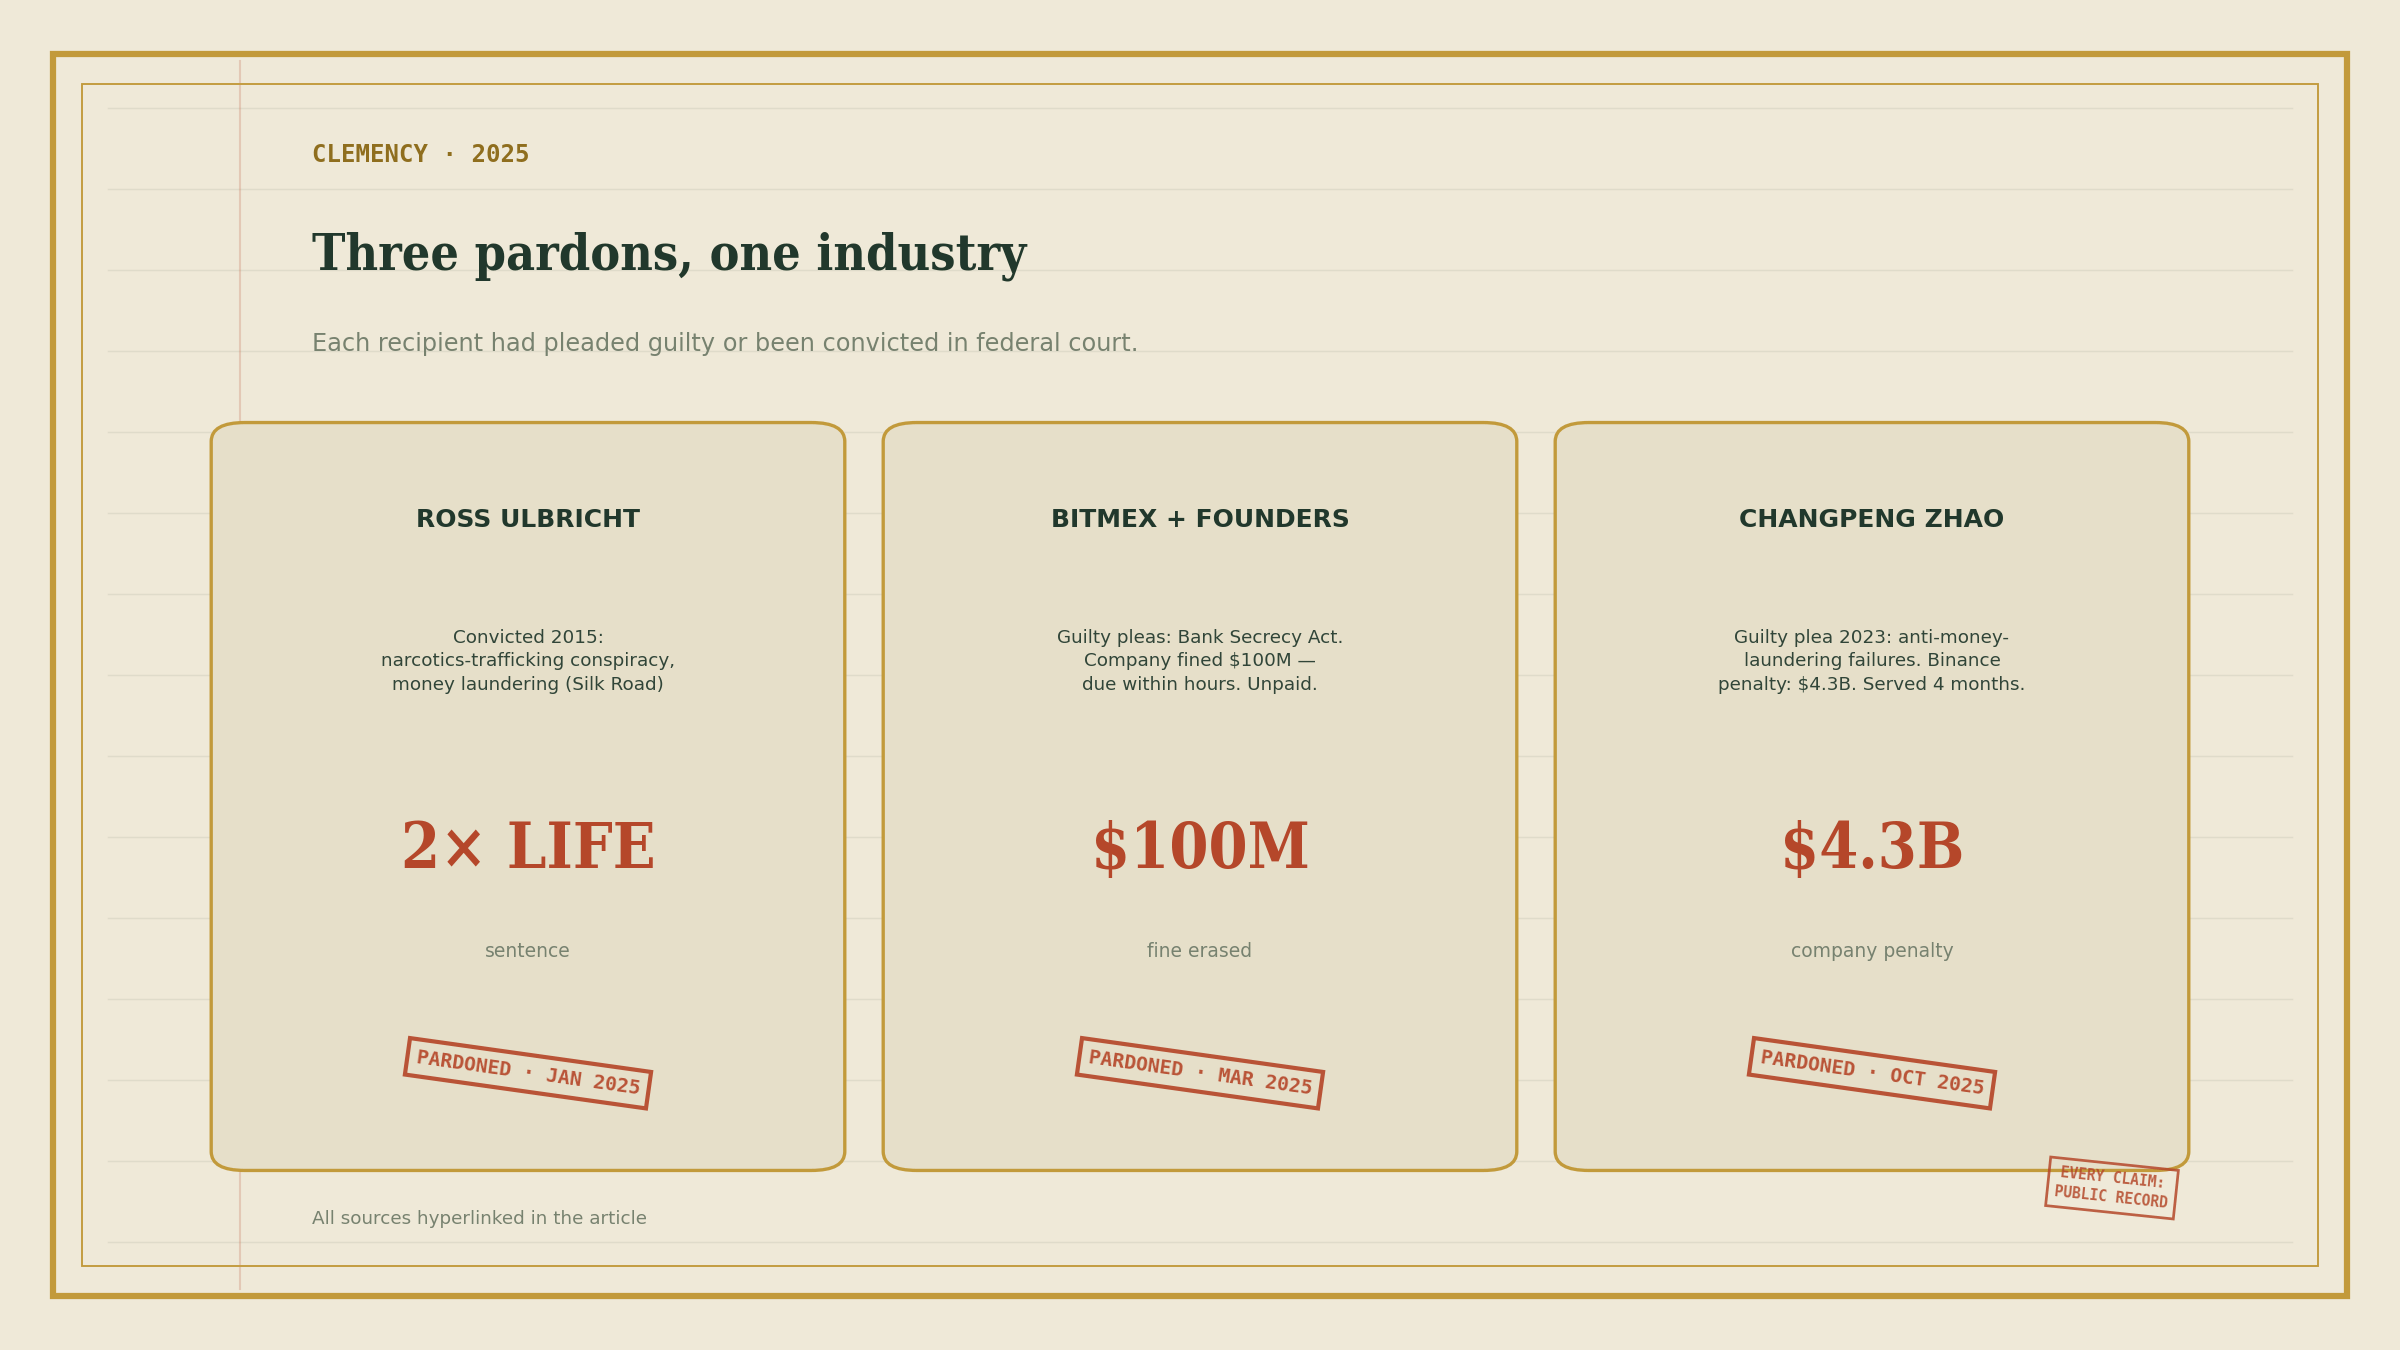
The largest pardon came in October. Binance is the biggest crypto exchange on earth, and in 2023 it pleaded guilty and agreed to pay more than $4.3 billion - among the largest corporate penalties in American history. The government’s findings deserve to be stated specifically, not brushed aside as “compliance failures.” According to the Justice Department, Binance failed to prevent or report transactions involving Hamas’s al-Qassam Brigades, Palestinian Islamic Jihad, al-Qaeda, and ISIS; a Congressional Research Service report records the Qassam Brigades - the armed wing of Hamas - using Binance from as early as 2019. The company admitted that users in Iran, Cuba, Syria, and Russian-occupied Ukraine moved money through it, in violation of U.S. sanctions. The Treasury Secretary at the time said Binance’s failures “allowed money to flow to terrorists, cybercriminals, and child abusers.”
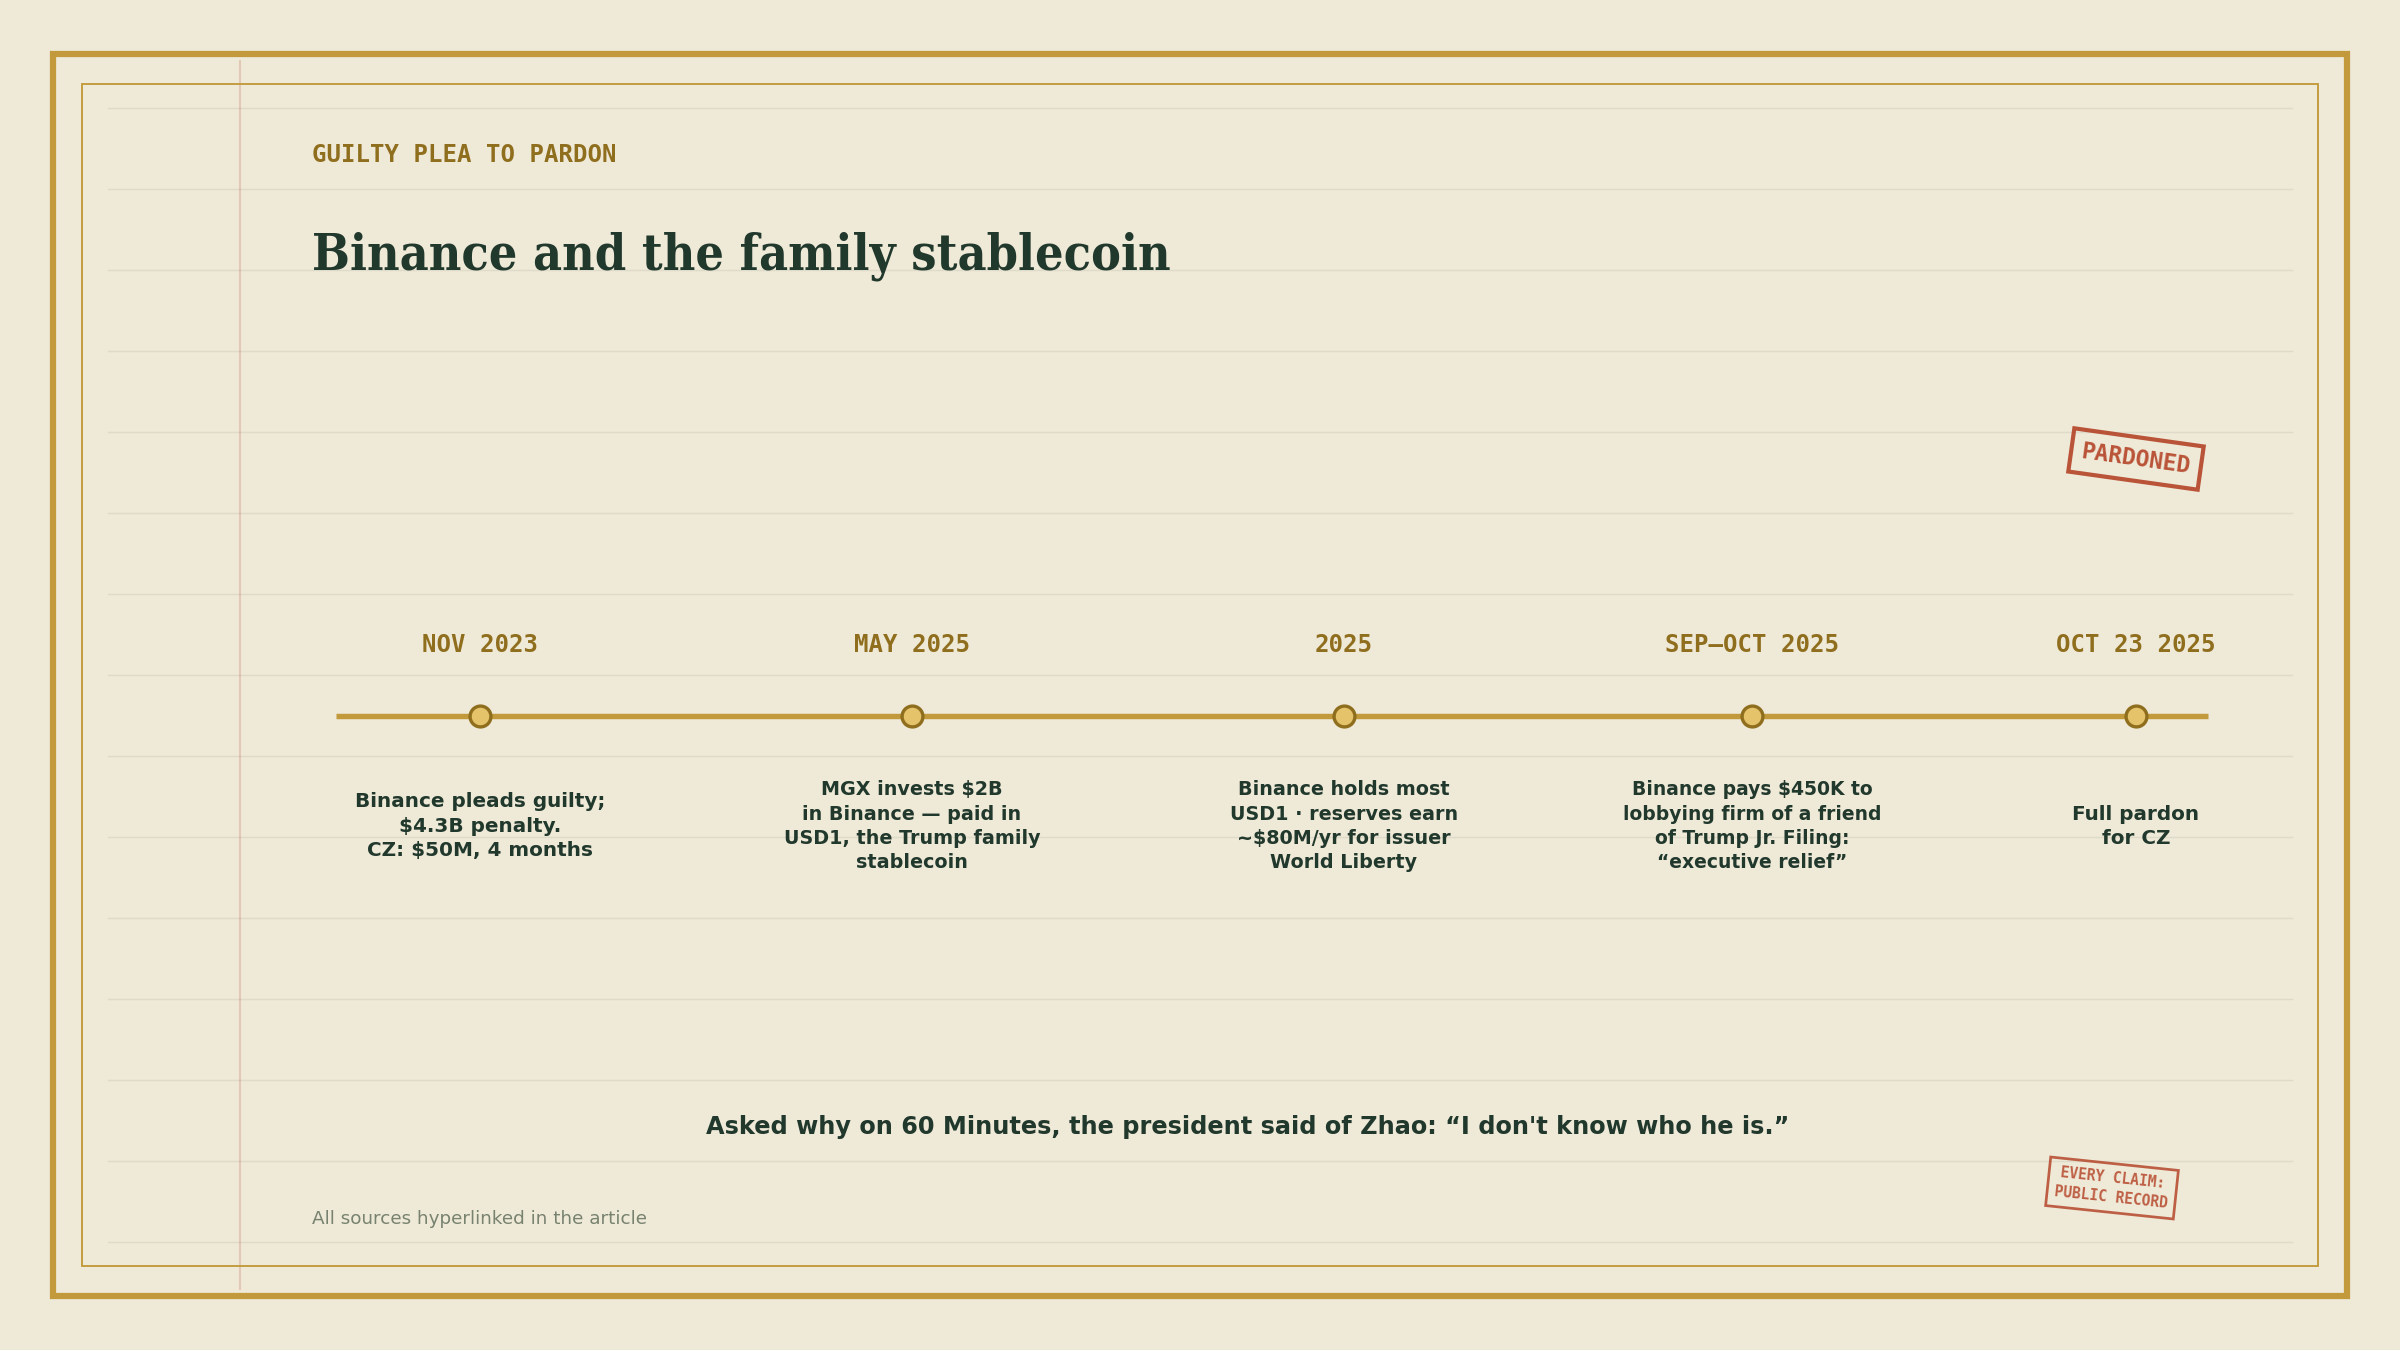
Its founder, Changpeng Zhao - “CZ” - pleaded guilty personally, paid $50 million, resigned, and served four months. Trump pardoned him in October 2025, with the White House recasting the prosecution as a Biden “war on cryptocurrency” with no identifiable victims. Trump, asked on 60 Minutes why he did it, said he didn’t know who Zhao was. Disclosure records show that in the weeks beforehand, Binance had paid $450,000 to a lobbying firm run by a friend of Donald Trump Jr., which reported lobbying the White House for “executive relief” - the industry term for a pardon. And the claim not to know Zhao omits something much larger - documented later in this story. By the time of the pardon, Binance had already helped put two billion dollars to work for the Trump family’s own crypto company.
Calling off the police
The Securities and Exchange Commission is the agency that polices American financial markets. Under chair Gary Gensler, it had sued much of the crypto industry - Binance, Coinbase, Kraken, Ripple, Robinhood - on a consistent theory: Alleging these firms were running stock-market-like businesses and selling investment products without registering under the investor-protection laws that bind everyone else who does those things. In the Binance case, the SEC alleged an extensive web of deception and calculated evasion of the law.
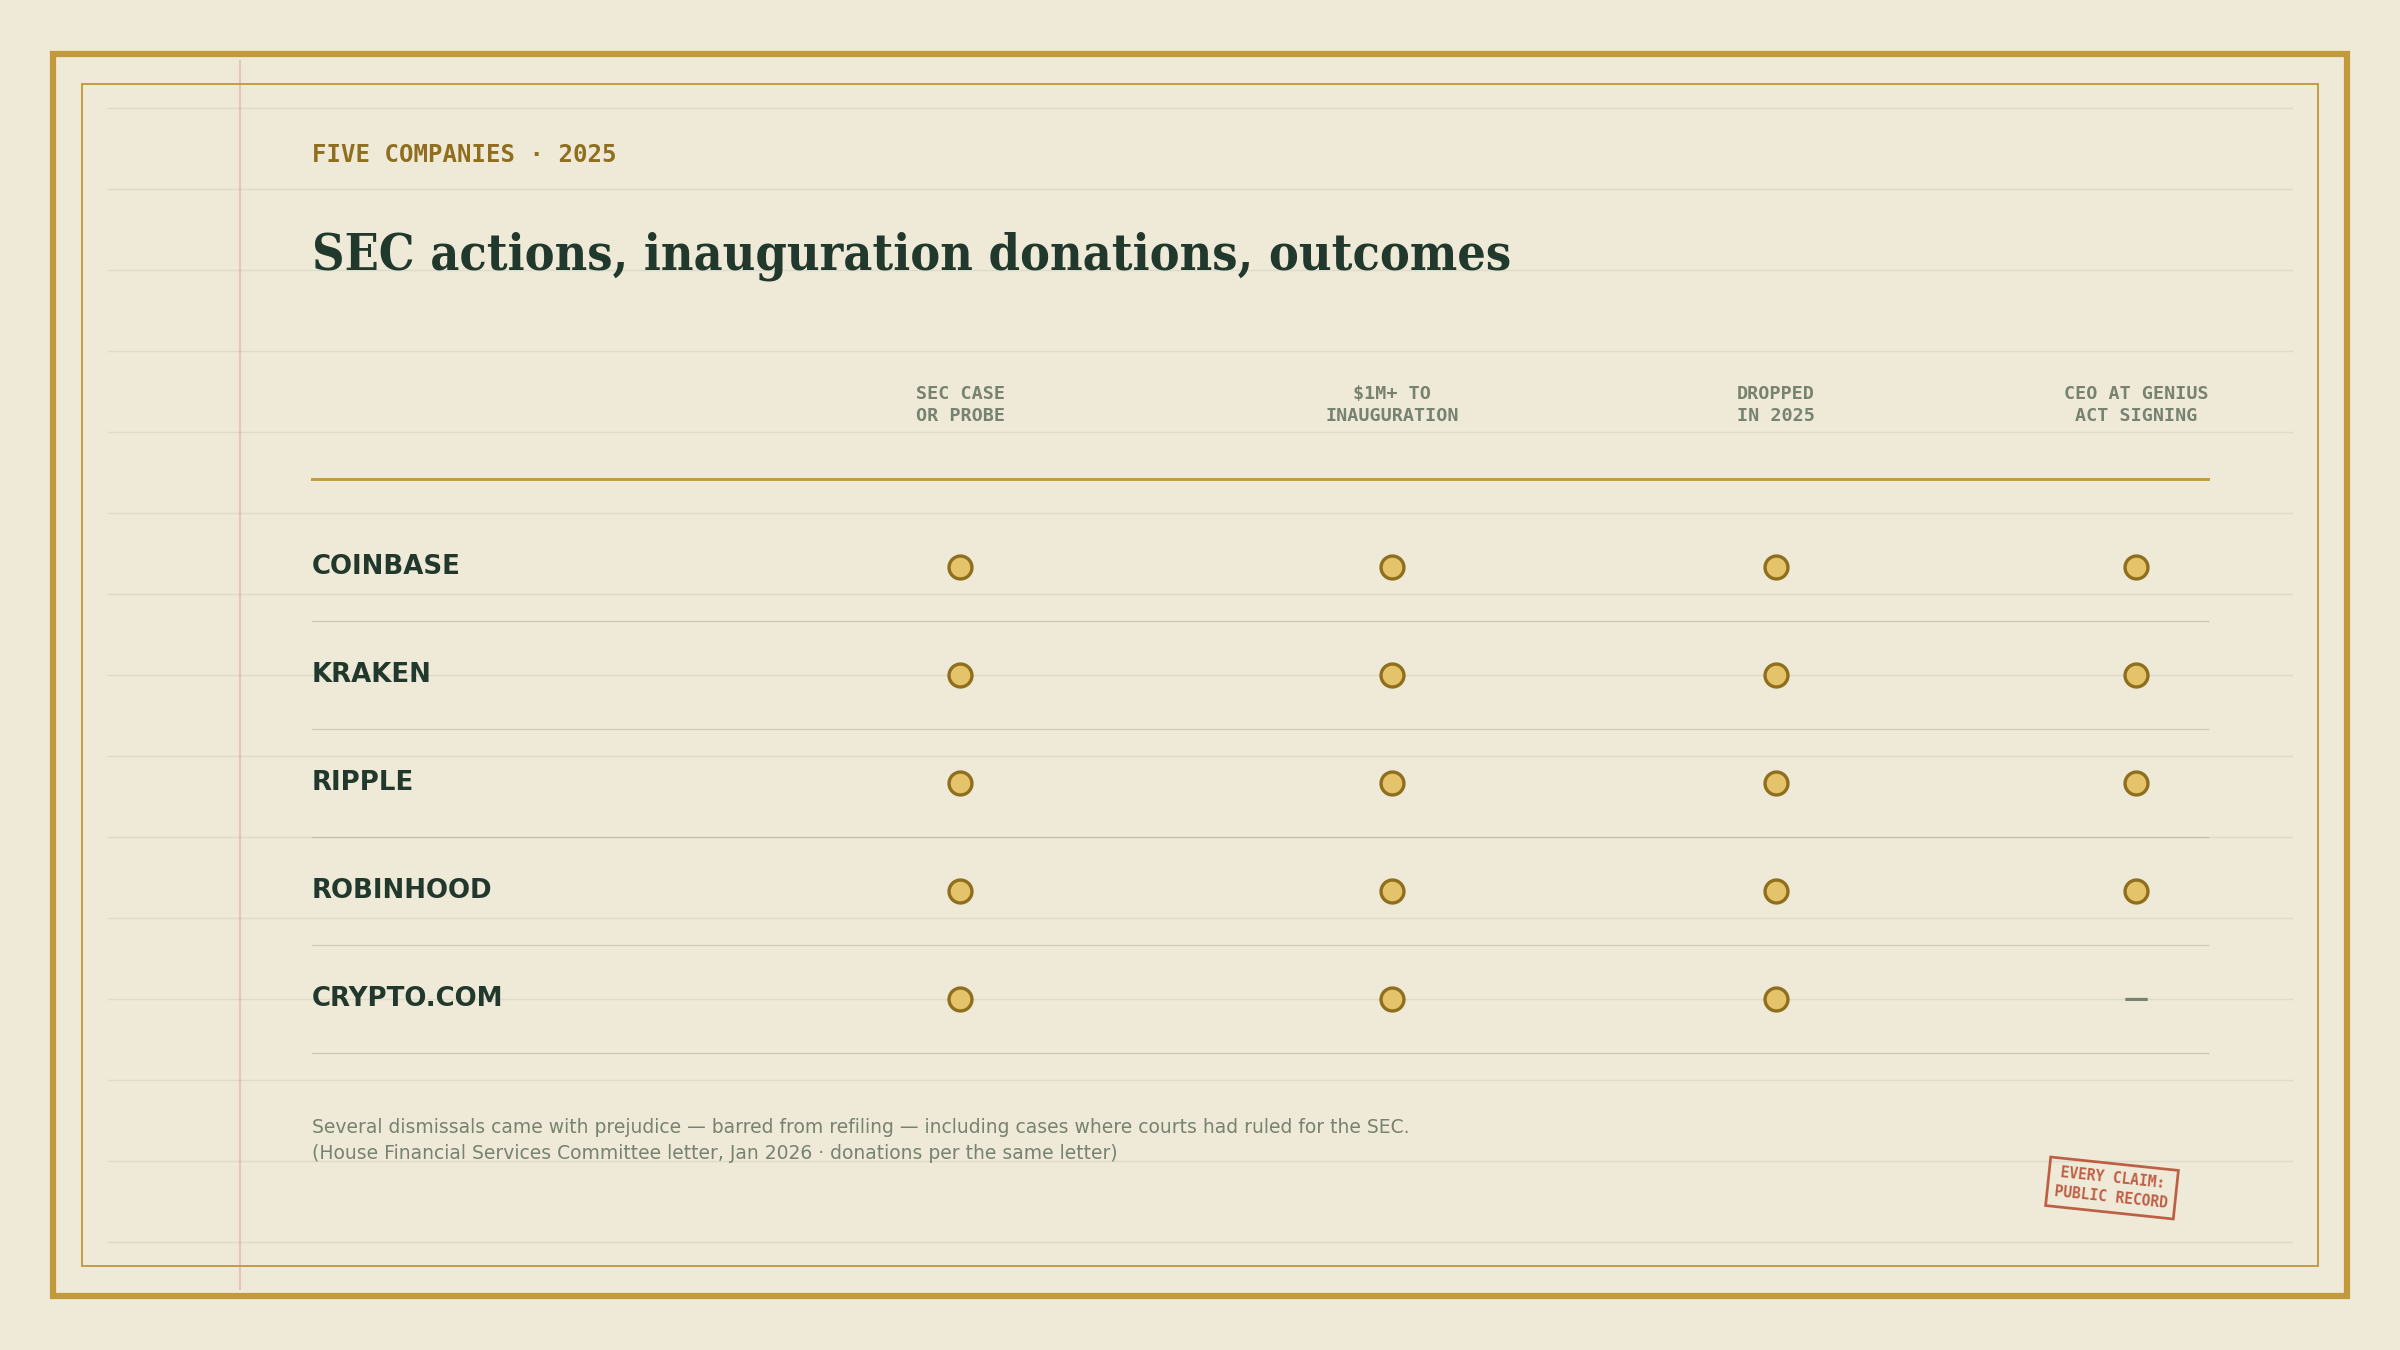
Gensler left the day Trump was inaugurated. His successor, Paul Atkins, was a longtime crypto advocate, reportedly holding up to $6 million in crypto-related investments. Within months, the commission dropped the cases against Coinbase, Binance, Kraken, Ripple, Robinhood and others - many dismissed “with prejudice,” a term whose meaning is undoubtedly deliberate. Those charges can never be refiled, by this administration or any future one.
A letter from members of the House Financial Services Committee assembled the details that turn a change in priorities into something else. Several cases were dropped after courts had already ruled for the SEC on central questions - the government was winning, and surrendered anyway. Companies whose cases or investigations were dismissed, including Coinbase, Kraken, Ripple, Robinhood, and Crypto.com, had each given at least $1 million to Trump’s inauguration. The lawmakers wrote that the pattern created the unmistakable inference of a pay-to-play scheme.
The Justice Department disbanded its specialized crypto enforcement team - the unit whose work produced the Binance and BitMEX guilty pleas, the very convictions being pardoned. By fiscal year’s end the SEC had filed fewer enforcement actions than in any prior year in at least two decades. They defunded the police on behalf of the prosecuted’s funds.
The consequences did not wait. In 2026, the Wall Street Journal reported that Binance had fired employees who flagged a billion dollars flowing to sanctioned Iranian entities through its platform. The same kind of conduct it admitted to in 2023, allegedly continuing after the plea, after the monitorship, and after the pardon. They also reported the Justice Department had opened a probe of Iran’s use of the exchange. American victims of the October 7 attacks have sued Binance and Zhao, alleging the platform processed over a billion dollars for Hamas, Hezbollah, Palestinian Islamic Jihad, and Iran’s Revolutionary Guard.
The regulators who joined the regulated
Two appointments define the administration’s philosophy as clearly as any pardon.
David Sacks, a venture capitalist from the founding PayPal circle, became the White House czar for artificial intelligence and cryptocurrency - a private investor in the industry handed the job of writing the industry’s rules. The referee position went to a player, openly and by design.
The second case is more strange. Bo Hines was twenty-nine, a former college wide receiver who had lost two congressional races and had, by the accounts of the trade press covering his appointment, limited crypto experience. He was made executive director of the President’s Council of Advisers on Digital Assets - in other words, the operational lead for national crypto policy. In just seven months, he helped push the industry’s most important bill through Congress. Then he quit.
Days later, he was working for Tether, the world’s largest stablecoin company - the company Brock Pierce co-founded - soon becoming chief executive of its new U.S. division.
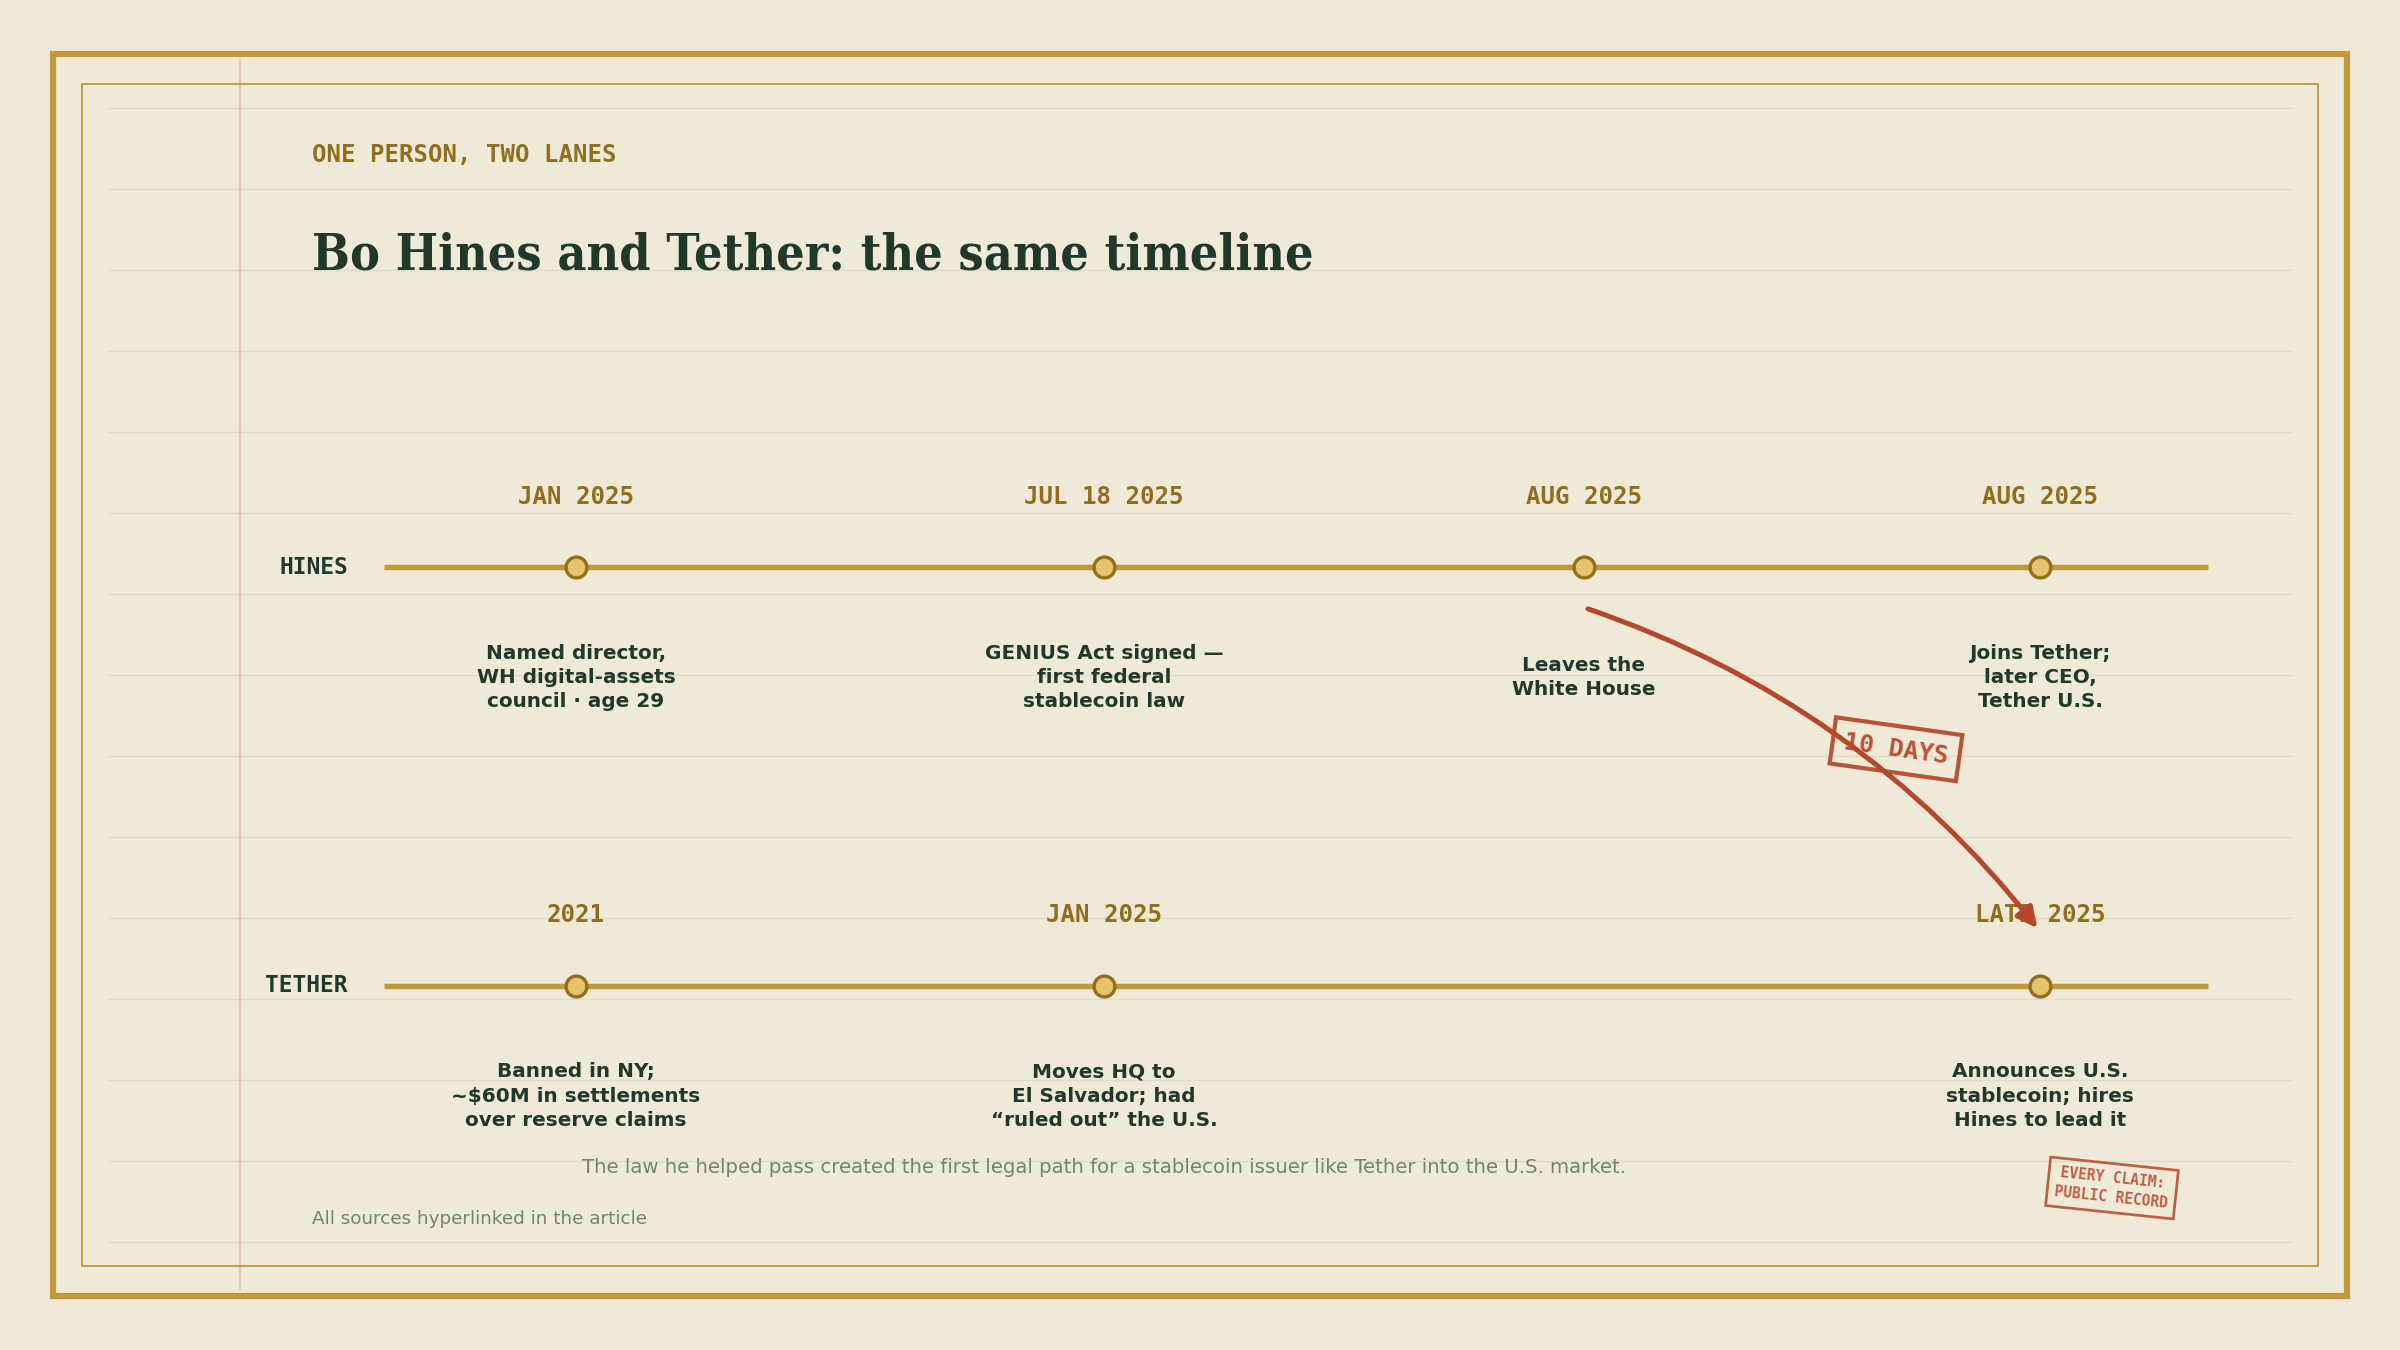
Tether’s history explains what that job is worth. The company spent years arranged offshore, in the British Virgin Islands, beyond American regulators’ reach. It was banned from New York and paid nearly $60 million in 2021 to settle claims it made false statements about the reserves behind its coin, and it has faced a reported Justice Department investigation. In January 2025, the month Trump took office, Tether moved its headquarters to El Salvador - a jurisdiction offering crypto firms a fifteen-year tax exemption - and per Reuters, said it had “ruled out” the United States over regulatory uncertainty.
Then the law changed - the law Hines helped write - and the uncertainty resolved itself. Tether announced a U.S.-market stablecoin and hired the man who had just run the White House crypto council to lead its American entry. A company that spent a decade positioning itself beyond American law walked through the front door the moment its future executive finished constructing it.
One more of Tether’s Washington connections belongs here. The U.S. Treasury bonds backing its coin are custodied primarily by Cantor Fitzgerald - the firm Howard Lutnick ran for three decades before becoming Trump’s Commerce Secretary. Lutnick did not hand the firm to strangers once he took office. Upon confirmation, he installed his sons: Brandon, 27, as chairman and chief executive, and Kyle, 28, as executive vice chairman, and later transferred his ownership into trusts benefiting his children, with Brandon as controlling trustee. As Fortune noted at the time, the sons would be “key players” in crypto, precisely because of Cantor’s alliance with Tether. The arrangement has been good to them: under the brothers, Cantor rode the crypto boom to a record year, with revenue climbing past $2.5 billion, all while denying any conflict with their father’s cabinet post. So the Commerce Secretary’s family firm banks the reserves of the company that hired the White House’s crypto director, whose product the White House’s own law legalized. The circle is small, and every seat in it is related to someone.
A law with holes where the protections go
That law is the GENIUS Act, signed July 18, 2025 - the first federal framework for stablecoins.
A stablecoin is a digital token engineered to always be worth one dollar. It functions as the cash of the crypto economy. The business model is the point. When a customer buys $100 of a stablecoin, the issuer takes the real hundred dollars, invests it in interest-paying assets like Treasury bonds, and keeps the interest. The customer holds the tokens; the issuer holds the money. At scale this resembles banking without a banking charter - Tether alone now holds roughly $141 billion in U.S. Treasury debt, a position the size of a midsize nation.
The GENIUS Act blessed the model and removed stablecoins from the securities laws the SEC had used to sue the industry. Its omissions drew warnings before the ink dried. State prosecutors, led by New York’s attorney general, noted the law contains no requirement that issuers return stolen funds to fraud victims - which lets issuers keep and profit from the proceeds of fraud. Senators objected that it includes no safeguard against the president’s own conflicts of interest - an omission whose purpose the next section makes plain, because the president’s family issues a stablecoin of its own.
The bill passed with real bipartisan margins, 68-30 in the Senate and 308-122 in the House, after the industry spent more than $130 million electing crypto-friendly candidates in 2024, and became the largest corporate contributor to the elections that followed. In 2026 alone, Reuters reports they have spent over $189 million to influence midterm election. The scene at the signing is preserved in the White House’s own press release: Coinbase chief executive Brian Armstrong, Ripple chief executive Brad Garlinghouse, Kraken co-chief executive Dave Ripley, Robinhood chief executive Vlad Tenev, Paxos chief executive Charles Cascarilla, and Chainlink co-founder Sergey Nazarov, among others, celebrating in the room. Four of those companies - Coinbase, Ripple, Kraken, and Robinhood - had watched the SEC’s lawsuits or investigations against them evaporate within the year, following their million-dollar inauguration checks. Now their executives stood behind the president as he signed their industry’s law.
The family business
Trump spent years publicly disparaging cryptocurrency before reversing himself during the 2024 campaign. He said it seemed like a “scam,” and didn’t like “another currency competing against the dollar.” His reversal coincided with his own family entering the crypto-business as one of its principal players. The empire now runs on several engines, and the government the family controls has taken official action benefiting each.
World Liberty Financial is the flagship, launched weeks before the 2024 election: a crypto venture co-founded by Trump, his sons Eric, Don Jr., and Barron, and the sons of Steve Witkoff, as seen in the SEC filing. The Witkoff name matters as much as the Trump name here. Steve Witkoff is the administration’s special envoy to the Middle East - the American official personally negotiating with the Gulf states, including the United Arab Emirates, on the region’s wars, investments, and strategic arrangements. His son Zach runs World Liberty as chief executive. The family takes 75 percent of net proceeds from token sales. Its products are a token, $WLFI, and a stablecoin, USD1 - which means everything just explained about the stablecoin business model now applies to the first family: every dollar parked in their coin earns them interest.
Watch what happened around this company, in sequence, with the Witkoffs’ government role in mind.
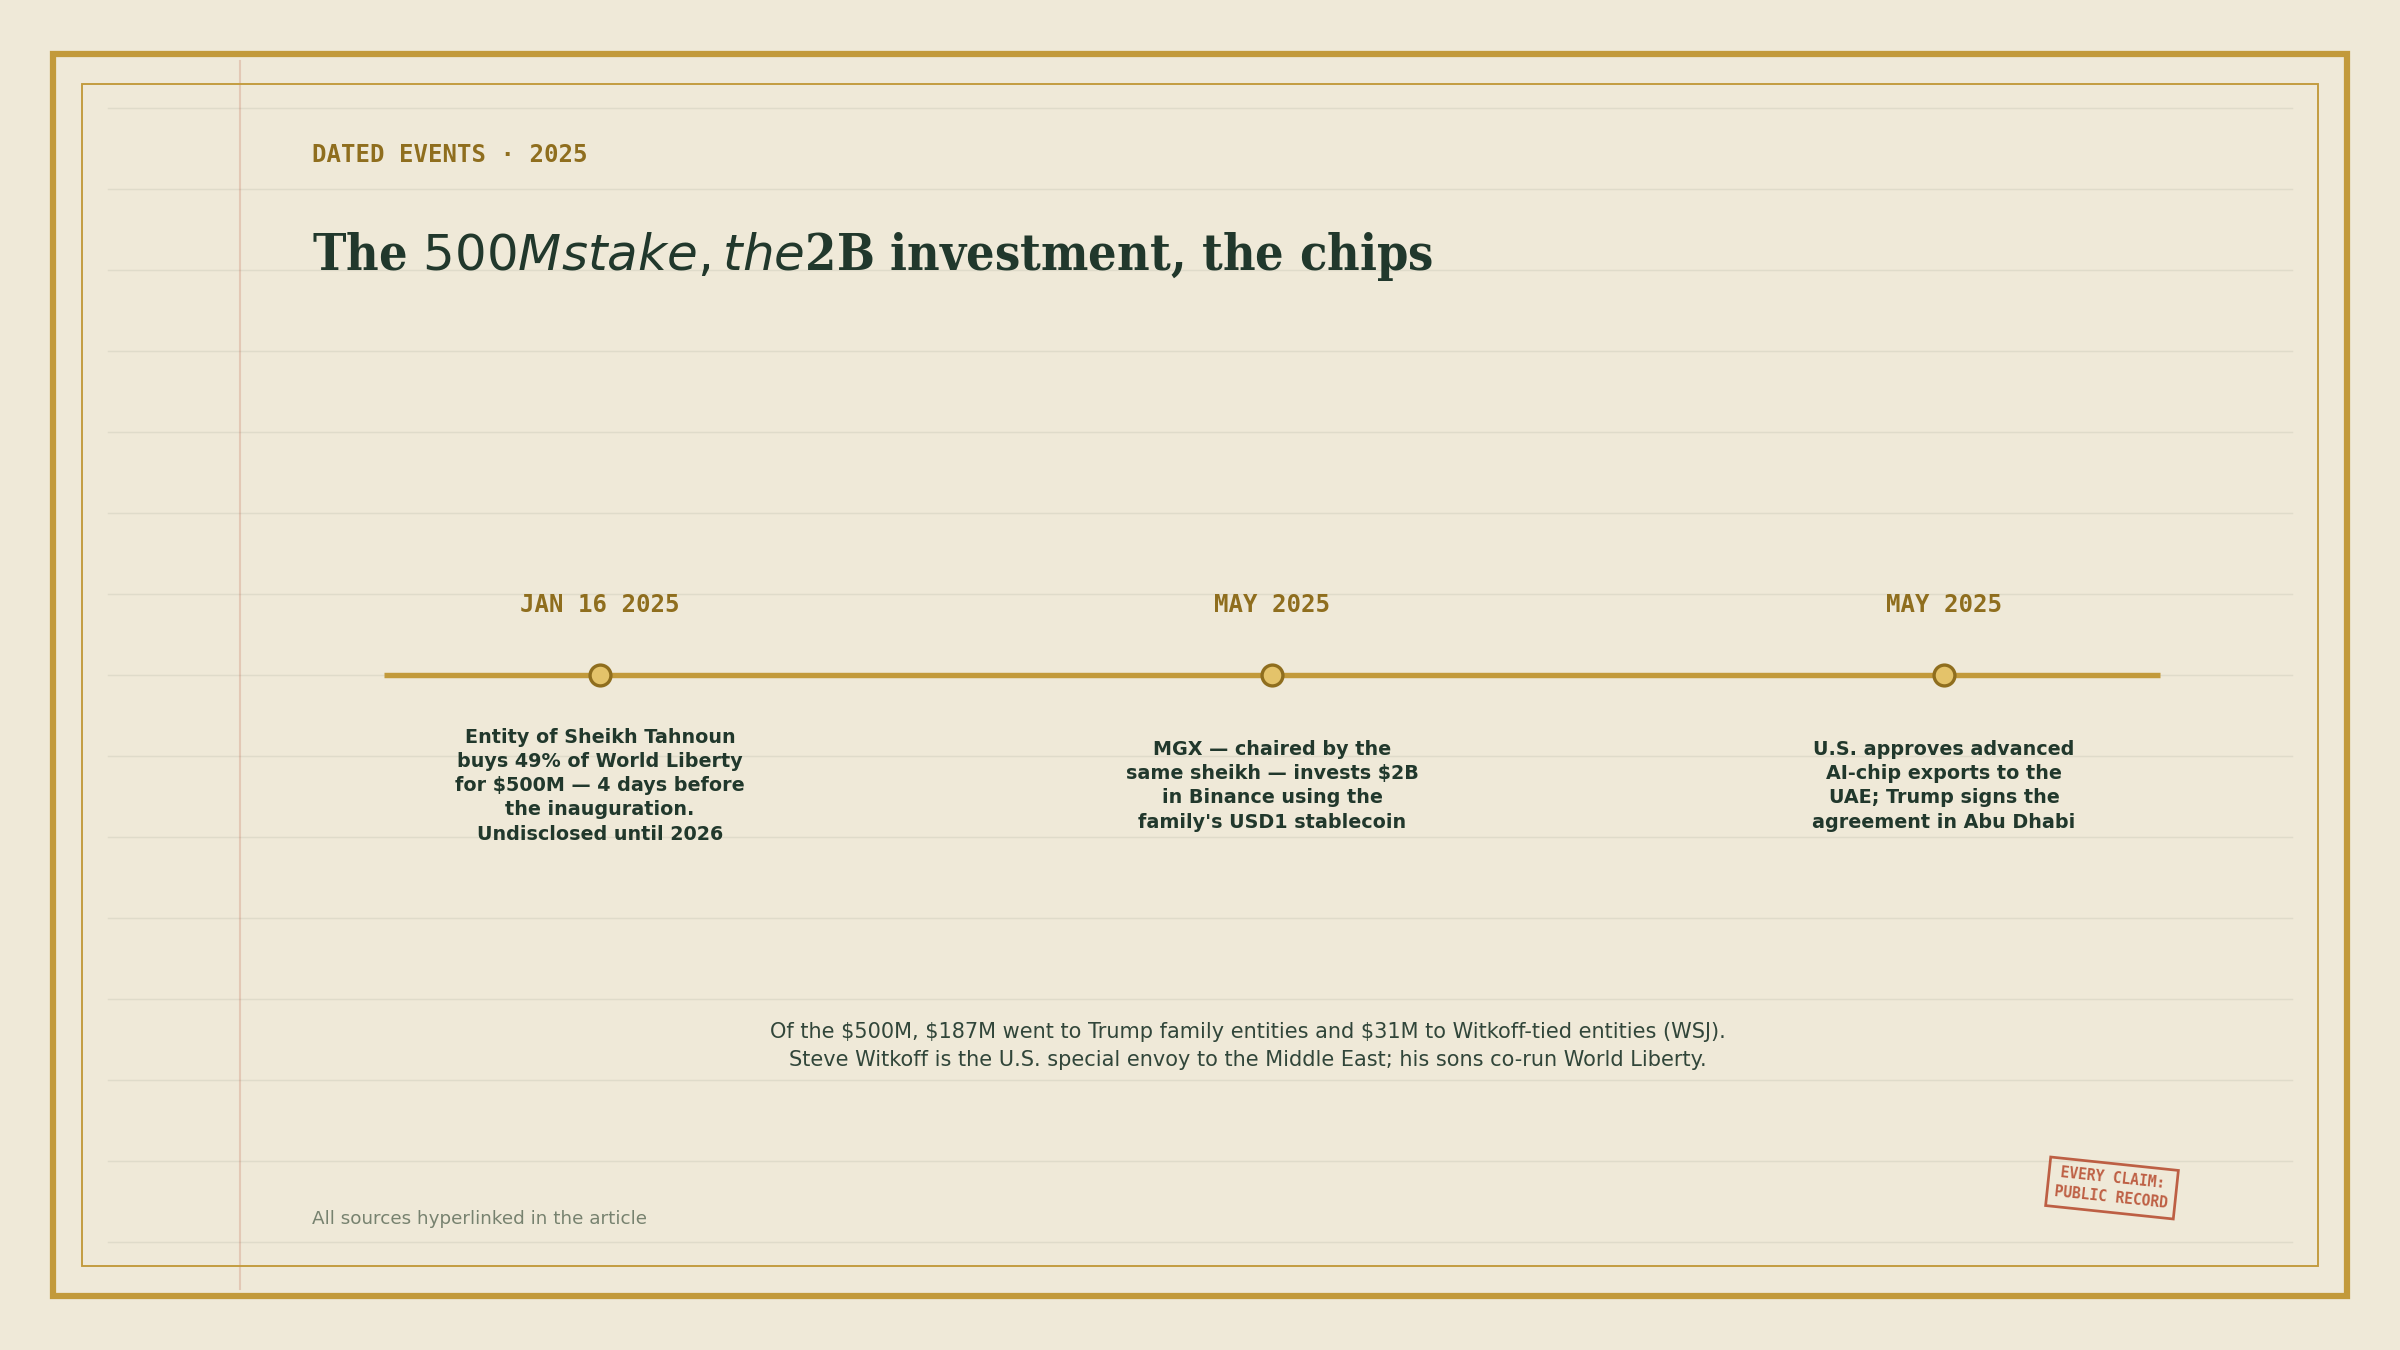
Four days before the inauguration, an entity controlled by Sheikh Tahnoun bin Zayed Al Nahyan - Abu Dhabi’s deputy ruler and the UAE’s national security adviser - secretly bought 49 percent of World Liberty Financial for half a billion dollars, routing $187 million to Trump family entities and $31 million to entities tied to the Witkoffs. The purchase stayed hidden until the Wall Street Journal exposed it in 2026. Then, in May 2025, MGX - another fund chaired by the same sheikh - put $2 billion into Binance, paid in World Liberty’s stablecoin. Under the stablecoin model, those coins in circulation let World Liberty collect roughly $80 million a year in interest for the Trumps and their partners. Binance was not a bystander. It holds most of USD1’s supply, and a Binance-operated platform partnered with World Liberty to help build it’s technology and promote the coin. The company built the Trump stablecoin into a top product, then its founder received his pardon from a president claiming not to know him.
What happened next is also on the record. After the Emirati money had flowed to the family, the administration approved supplying the UAE with hundreds of thousands of advanced American AI chips - Nvidia and AMD processors are among the most strategically guarded exports the United States has - over national security objections. Trump traveled to Abu Dhabi to sign the arrangement personally. This is where the special envoy’s portfolio and his family’s balance sheet intersect. The government officials shaping America’s Middle East relationships were, through their children, business partners of the Middle Eastern royal whose funds had just enriched them. Forbes later reported that Witkoff substantially enriched himself during his government tenure, largely through World Liberty; legal scholars have called the UAE dealings a potential violation of the Constitution’s emoluments clause, the founders’ ban on presidents taking payments from foreign states. World Liberty has since applied for a federal trust bank charter, which would let the family’s company custody the reserves behind its own coin under the framework the family’s administration created. (Kait Justice has done extensive reporting on what this would mean if approved.)
The meme coin is the second engine. Days before the inauguration, Trump launched $TRUMP, a token with no purpose beyond speculation on his name; his 2025 disclosure reports more than $635 million in royalties tied to the coin venture.
American Bitcoin is the third, and it reaches into something every American now pays for. In March 2025, Eric Trump and Donald Trump Jr. partnered with the mining firm Hut 8 to launch a Bitcoin mining company, with Eric as co-founder and chief strategy officer. Bitcoin mining is the industrial computing that mints new coins, and it is done in data centers - warehouses of machines whose defining appetite is electricity. Hut 8, which operates the Trumps’ machines, controls more than a thousand megawatts of energy capacity; Eric Trump has said the mining race will be won in the “cheapest energy environments,” and his father’s energy policy has explicitly opened resources to digital mining.
The context ordinary readers will recognize is their power bill. American retail electricity prices have climbed nearly 40 percent since 2021, with households paying on average $110 more last year than the year before. Data centers are not the only cause - grid upgrades and weather damage matter too - but on the largest grid in the country, serving 65 million people across thirteen states, the grid’s own independent market monitor has identified data center load growth as the primary reason for record-high prices, and a study of future costs includes cryptocurrency mining in its modeling of why national wholesale prices could keep climbing through the decade. Seven in ten Americans now say they don’t want a data center near their home. The president’s sons operate in exactly this business - their company went public on the Nasdaq at a valuation near $5 billion and accumulated thousands of Bitcoin on its balance sheet, while employing, per Fortune, about five people and paying Hut 8 to do the work - as their father’s government sets the energy policy the business depends on.
The venture’s returns, it turns out, were less durable than its access. As of this week, American Bitcoin’s shares have fallen more than 95 percent from their peak, erasing over $600 million from the market value of Eric Trump’s stake, by Bloomberg’s calculation. The company posted a $118 million first-quarter operating loss as Bitcoin’s price sank, and executed a 1-for-15 reverse stock split to preserve its Nasdaq listing. The detail with a certain symmetry: Rival miners that pivoted their data centers toward AI have thrived, and even Hut 8 - the firm that runs the Trumps’ machines - leaned into multibillion-dollar AI data-center leases while the family’s company stayed all-in on the coin. The public still pays the grid costs of the boom either way. The family’s paper losses do not refund anyone’s electric bill.
There is also the public’s money. In March 2025, Trump ordered the creation of a Strategic Bitcoin Reserve, committing the United States government itself to holding the asset his family mines and markets. The totals, from the records: Trump’s own disclosure shows more than $1 billion in personal crypto income last year. Reuters put the family’s crypto gains during the term at no less than $2.3 billion. Crypto is now, by some measures, the largest source of the president’s fortune.
Which leaves the question of who talked him into the reserve.
The Manafort thread, and what it is doing to Britain
Part of the answer is Paul Manafort.
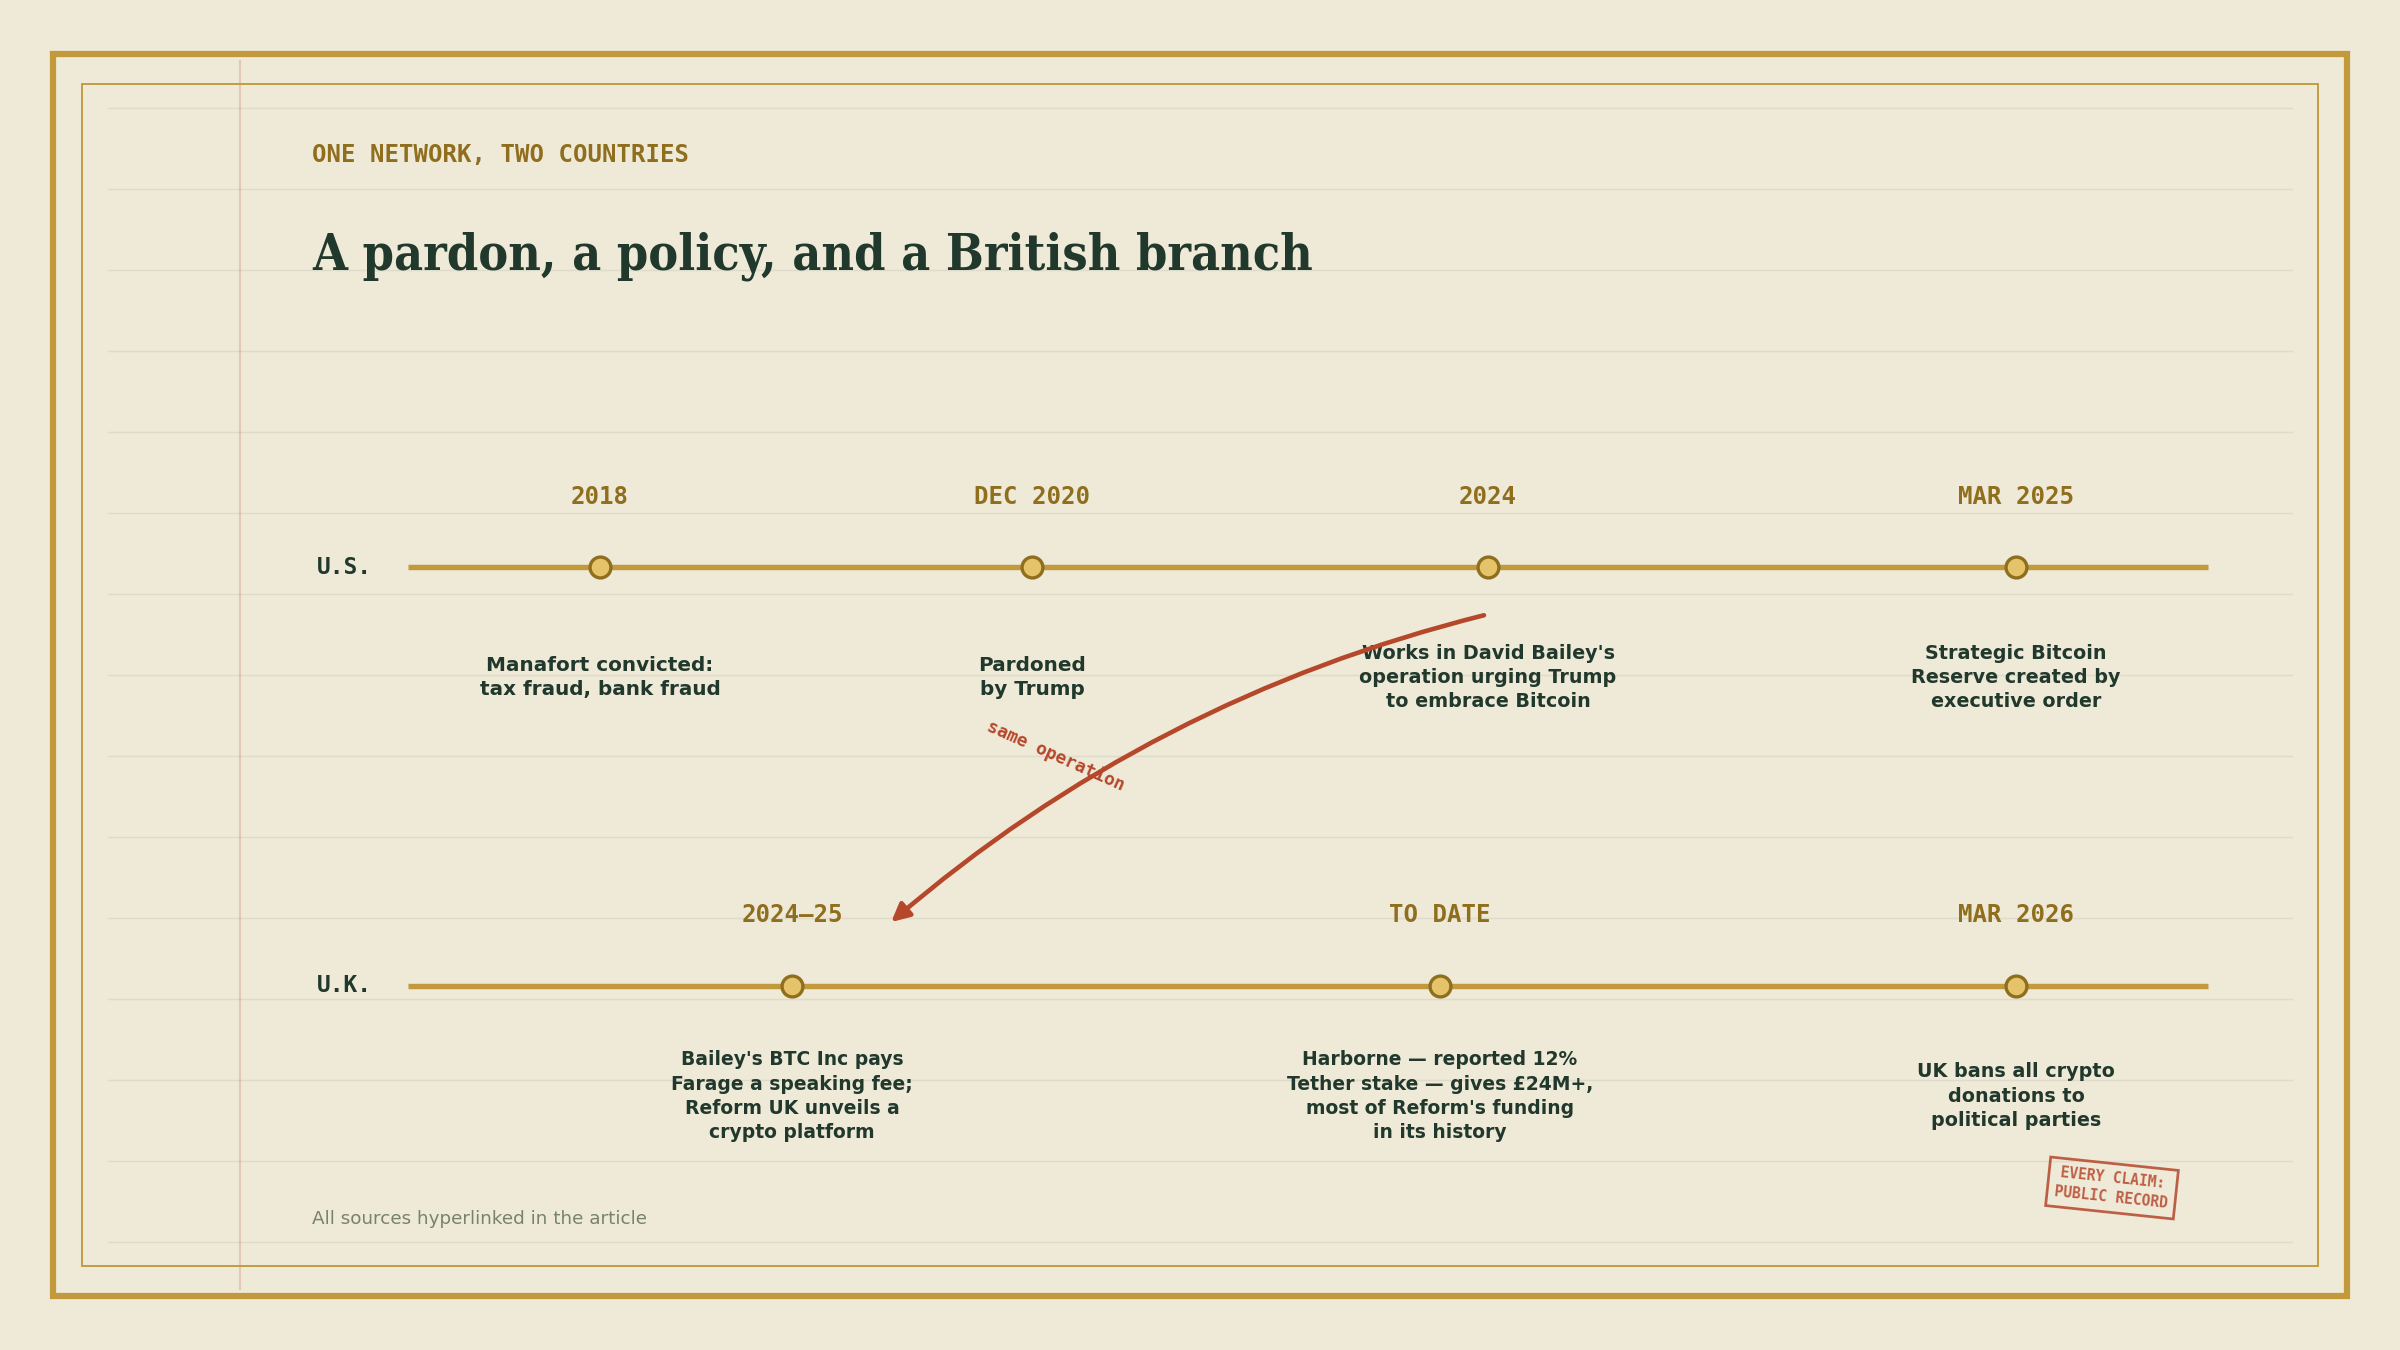
Manafort chaired Trump’s 2016 campaign and was convicted in 2018 of tax fraud and bank fraud arising from his work for Kremlin-aligned interests. A bipartisan Senate Intelligence Committee investigation concluded his activities were a grave counterintelligence threat to the United States, documenting that as campaign chairman he passed internal polling data to a man the committee identified as a Russian intelligence officer. Trump pardoned him in December 2020.
Pause on that pardon, because it is the hinge of this section. A convicted felon cannot lobby a president from a prison cell. Every part of what Manafort did next was possible only because Trump had wiped his convictions away - which means the crypto pardons of 2025 were not the beginning of this machine. The machine’s own architect was a product of clemency. According to reporting by Byline Times, Manafort resurfaced in early 2024 inside the lobbying operation of David Bailey -chief executive of BTC Inc and a senior crypto adviser to Trump - and spent that year working with Bailey to persuade Trump to embrace Bitcoin and create the Strategic Bitcoin Reserve. A man the Senate called a counterintelligence threat, freed by one Trump pardon, spent 2024 designing the crypto policy of the administration that would go on to issue the rest of them.
The same network now runs through British politics. Bailey’s company paid Nigel Farage a speaking fee months before the Reform UK leader unveiled a crypto platform mirroring the Trump administration’s, including a proposed British state Bitcoin reserve. Reform’s money is a crypto story in itself: Christopher Harborne, a Thailand-based British billionaire holding a reported 12 percent stake in Tether, has directed more than £24 million to Farage’s party and its predecessors - roughly two-thirds of everything Reform has ever raised - making him the largest political donor in British history, on top of an undisclosed multimillion-pound personal gift to Farage now under review by Parliament’s standards commissioner. The Guardian later reported the gift amounted to £5 million.
Britain’s response measures how seriously another democracy takes what Washington has normalized. After an independent review found worsening foreign interference in UK politics - naming the opacity of cryptocurrency as a principal vulnerability - the government imposed an immediate moratorium on all crypto donations to political parties, with no threshold and no exceptions. The instrument reshaping American policy from inside the White House was, across the Atlantic, banned from politics outright.
The old money
Which returns this story to the man with the scissors - and to where his industry’s early money came from.
The Justice Department’s release of the Epstein files shows that Epstein - years after his 2008 conviction - was an early investor in the companies that became crypto’s establishment. Through a Virgin Islands entity, he put roughly $3 million into Coinbase’s 2014 funding round - the company whose chief executive later stood at the GENIUS Act signing - and invested in Blockstream, a foundational Bitcoin infrastructure firm. Pierce, then running the venture firm that became Blockchain Capital, was the one who brought Epstein the Coinbase deal. To be precise about the record: Neither Coinbase, nor Blockchain Capital, nor Pierce has been linked to any wrongdoing in regard to Epstein’s crimes. What the files document, in the men’s own words, is the closeness - and where the money went.
The correspondence, released by the Justice Department shows the relationship between Epstein and Brock Pierce spanned nearly a decade, appearing to begin after Epstein’s first conviction. In a 2012 message, Pierce told Epstein he “had a great time with the girls”; after Epstein asked him during a Ukraine trip to take photos and find him a present, Pierce responded, “will do,” with a smile. The favors ran in both directions, and the files record one in detail. In a March 2018 email, Pierce asked Epstein if he knows the best way to get in contact with Alan Dlugash, the man who helped Epstein with his own taxes. Regarding Pierce, Epstein told Dlugash, “says he hasn’t filed a return in 5 years.” The timing gives the favor its context: this was early 2018, the same window in which Pierce’s firm wired Epstein $15 million for half his Coinbase stake - five times what Epstein had put in. A convicted sex offender was collecting an eight-figure crypto windfall while quietly arranging tax help for a co-founder of Tether.
Be concrete about where that $15 million landed. Epstein was alive and free when it arrived, a year before his final arrest, and a Senate Finance Committee investigation into his money stated plainly that his income funded his sex trafficking operation. Crypto’s early gains did not enrich an abstraction.
Pierce followed the industry’s standard geography, relocating to Puerto Rico in 2017, where crypto wealth is sheltered from federal income tax - the same offshore pattern as Tether’s British Virgin Islands years and its El Salvador tax holiday. And he has not receded. Before this spring’s ribbon-cutting at Doral, he had appeared at Trump’s second inauguration carrying a miniature of the same golden statue. The man who walked Epstein’s money into crypto’s founding companies still stands inside the president’s world, scissors in hand.
The ledger
Set the events in order and the through-line is money.
The industry spent $130 million electing a government. The government pardoned the industry’s convicted executives - including the first corporation ever pardoned in American history, hours before its $100 million debt to a crime victims’ account came due - and justified the clemency with a persecution story the guilty pleas themselves refute. The agencies that had won those cases quit fighting, permanently dismissing suits they were winning, against companies that had each given a million dollars to the inauguration and whose chief executives then stood in the room as the president signed their law. That law legalizes a product with no protection for fraud victims and no restraint on a president who sells it - and the president’s family sells it, collecting billions, including half a billion dollars in a secret pre-inauguration deal from an Emirati royal and two billion in coin circulation from a convicted exchange, followed by American chips for the Emiratis, negotiated alongside a special envoy whose sons run the family coin company, and a pardon for the exchange’s founder. The nation’s official Bitcoin policy was sold to the president partly by a pardoned man the Senate called a counterintelligence threat, whose network is now the largest funding source in British politics and has already provoked a national ban there. The president’s sons mine Bitcoin in the data-center economy that the largest grid’s own monitor blames for record power prices, while their father’s government sets energy policy and their neighbors’ bills climb - and when their company’s stock collapsed 95 percent this year, the bills kept climbing anyway. And the government’s own released files show crypto’s founding money entangled with Jeffrey Epstein - whose profits financed his crimes, and whose $15 million Coinbase windfall arrived even as he quietly arranged tax help for the Tether co-founder who cut the ribbon on the golden statue.
Every sentence of that paragraph rests on a public document. The pattern was assembled here; the facts were assembled by courts, regulators, Congress, and the participants themselves, in their own filings and their own emails. Every sentence has a document behind it. The only open question is the one no document can answer: Whether anyone will do anything about it.
UPDATE: Hours after this published, the pattern of cancelled justice continued. Bloomberg Law broke the news that the Trump DOJ had ordered yet another crypto investigation to be dropped with prejudice. One that was brought by his own prior justice department. Read my breakdown of what that entails, here.
Sources: All claims link to court records, Justice Department and Treasury materials, congressional letters and reports, White House statements, SEC and financial disclosure filings, the Justice Department’s Epstein files release as catalogued by named outlets, or reporting by named outlets. Where individuals have not been accused of wrongdoing, that is stated in the text.
I'm so excited! Starting now!!!
Excellent! Wasn’t it Bannon who said to Epstein that they were getting close to having real power?
The crypto story + Cambridge Analytica and Brexit was a hit job. The Brexit campaign was 2015 the same time as Trumps first run.
This story should be required reading.